UP Board Solutions for Class 10 Commerce Chapter 16 Nationalisation of Banks in India

UP Board Solutions for Class 10 Commerce Chapter 16 Nationalisation of Banks in India

Nationalisation of Banks in India Objective Type Questions (1 Mark)

Question 1.
The first bill favouring nationalisation of hank was presented on:
(a) 23rd August 1953
(b) 23rd August 1963
(c) 23rd August 1973
(d) 23rd August 1983
Answer:
(b) 23rd August 1963

Question 2.
The name of the lady who presented the first bill in favour of nationalisation was:
(a) Mrs Subhandra Joshi
(b) Mrs Jyoti Rani
(c) Mrs Soniya Gandhi
(d) None of these
Answer:
(a) Mrs Subhandra Joshi

UP Board Solutions

Question 3.
The ordinance nationalising the bank was issued on ………
(a) 19th July 1996
(b) 19th July 1989
(c) 19th July 1969
(d) 19th July 1998
Answer:
(c) 19th July 1969

Question 4.
In the first instance ………. major banks were nationalised.
(a) 14
(b) 16
(c) 18
(d) 20
Answer:
(a) 14

UP Board Solutions

Question 5.
The government nationalised 6 more banks through an ordinance dated ………..
(a) 18th April 1970
(b) 19th April 1980
(c) 19th April 1970
(d) 18th April 1980
Answer:
(c) 19th April 1970

Question 6.
Which of the following banks is a nationalised bank in India? (UP 2019)
(a) Yes Bank
(b) Dena Bank
(c) Axis Bank
(d) None of these.
Answer:
(b) Dena Bank

Nationalisation of Banks in India Definite Answer Type Questions (1 Mark)

UP Board Solutions

Question 1.
When were 14 Banks nationalised in India? (UP 2016, 17)
Answer:
19th July 1969.

Question 2.
What is the number of nationalised banks in India?
Answer:
14.

Question 3.
Which is the number of banks which ordinance issued by the President of India on 16th April 1980?
Answer:
6.

Nationalisation of Banks in India Very Short Answer Type Questions (2 Marks)

Question 1.
Write names of those banks which were nationalised in April 1980.
Answer:

  1. Oriental Bank of Commerce
  2. Vijaya Bank
  3. Punjab and Sindh Bank
  4. Corporation Bank
  5. New Bank of India
  6. Andhra Bank.

UP Board Solutions

Question 2.
Write names of those banks which were nationalised in 1969.
Answer:

  1. Central Bank of India
  2. Bank of India
  3. Punjab National Bank
  4. Bank of Baroda
  5. United Commerical Bank
  6. Canara Bank
  7. United Bank of India
  8. Dena Bank,
  9. Union Bank (UPBoardSolutions.com) of India
  10. Allahabad Bank
  11. Syndicate Bank
  12. Indian Bank
  13. Indian Overseas Bank
  14. Bank of Maharashtra.

Question 3.
Give any two advantages of Nationalised Banks. (UP 2015)
Answer:
Two advantages of nationalized banks are as follows:
(i) Inter-Bank competition can be ended: There is unnecessary competition among Indian Banks which benefits no one. If all the banks are nationalised, this necessary competition will automatically (UPBoardSolutions.com) come to an end.

UP Board Solutions

(ii) Development of Specialised Banks: There is at present acute shortage of agricultural, industrial and Indian Foreign Exchange banks in the country. If the entire banking industry is nationalised, the government will surely take steps to a developed specialised banking institution in the country.

Question 4.
Give any two disadvantages of nationalised banks. (UP 2015, 18)
Answer:
Two disadvantages of nationalised banks are as follows:
(i) Violation of Financial Secrecy: The third argument against bank nationalisation is that it will violate the financial secrecy of individual depositors and of institutions.

(ii) Payment of Compensation: The Government will need (UPBoardSolutions.com) substantial funds to compensate the shareholders of private banks if it decides to nationalise them. The amount needed by the Government is estimated to be around Rs. 100 crores.

UP Board Solutions

Question 5.
Mention two main objectives of nationalisation of banks in India. (UP 2019)
Answer:

  1. To eliminate the concentration of economic power in few hands.
  2. To extend banking facilities to unbanked rural Areas.

Nationalisation of Banks in India Short Answer Type Questions (4 Marks)

Question 1.
What do you understand by the nationalisation of banks?
Answer:
After independence, the people started thinking on the lines of nationalisation, for overcoming the problems and defects of the trade and industries. The banking institutions were one of them, which despite social control could not satisfy the needs of the people. The development of banks was very erratic and the Indian money market was not organised.

The Indian commercial banks did not open their branches in rural areas of provided loans only to big industrialist and businessmen. The really needy persons such as farmers, cottage and small industries, artisans (UPBoardSolutions.com) etc. were deprived of this facility. Because of all these problems, the demand for nationalisation of banks became greater. The demand for nationalisation the banks was intensified, with the nationalisation of Imperial Bank.

UP Board Solutions

Question 2.
Give some arguments in favour of nationalisation of hanks.
Answer:
The following arguments were advanced in favour on nationalisation:
(a) Balanced Growth of Banks: At present, the private banks operate only in those areas where they get good business, hence, generally all the banks are in towns and big cities. With the nationalisation of banks, the (UPBoardSolutions.com) government will open the branches in those areas which do not have banking facilities. In this way, by nationalising the banks they would have balanced growth.

(b) Improvement of Efficiency: The Government banks in view of their vast resources are able to attract competent, trained and experienced staff more effectively than the private banks. Consequently, the level of operational efficiency is bound to be higher in Government banks in comparison to private banks.

(c) Utilisation of Bank Credit in National Interest: If the banks are allowed to be operated by private individuals, then the bank’s credit shall not be used in the interests of the nation. On the contrary, the bank’s credit will be utilised in the interests of these individuals who control the banks.

(d) Business Fluctuations can be checked: As is well known, a capitalist economy is all the time affected by business fluctuations. The slump and the boom follow each other at regular intervals. These fluctuations cause untold harm to the economy of the country. The government can keep effective control only if the banks are fully nationalised.

UP Board Solutions

Question 3.
Give some arguments against nationalisation of banks.
Answer:
The following arguments were advanced against the nationalisation of banks:
(a) Fall in the efficiency of services: At present, the banks provide efficient services on a lower rate to customers due to the competition among the banks. After nationalization the banks would not be able to provide (UPBoardSolutions.com) these kinds of facilities.

(b) Violation of Financial Secrecy: The third argument against bank nationalisation is that it will violate the financial secrecy of individual depositors and of institutions.

(c) Payment of compensation: The Government will need substantial funds to compensate the shareholders of private banks if it decides to nationalise them. The amount needed by the Government is estimated to be around (UPBoardSolutions.com) Rs. 100 crores.

UP Board Solutions

(d) Lack of Elasticity: The quality of elasticity is one of the important aspects of the banking system. With the nationalisation of banks, they will lose the quality of elasticity because they will have to take prior permission from his high officers before taking any decision.

UP Board Solutions for Class 10 Commerce

UP Board Solutions for Class 10 Commerce Chapter 7 Communication System

UP Board Solutions for Class 10 Commerce Chapter 7 Communication System

Communication System Objective Type Questions (1 Mark)

Question 1.
S. T. D. stands for:
(a) Subscribers Trunk Dialing
(b) Subscribers Telephone Dialing
(c) Subscribers Trunk Dialer
(d) None of these
Answer:
(a) Subscribers Trunk Dialing

Question 2.
A mobile telephone system was inaugurated in the year:
(a) 1987
(b) 1985
(c) 1989
(d) 1991
Answer:
(b) 1985

UP Board Solutions

Question 3.
The popular code available in the market are :
(a) X. Y. Z. Code
(b) A. B. C. Code
(c) Bentley Code
(d) A. B. C Code and Bentley Code
Answer:
(d) A. B. C Code and Bentley Code

Question 4.
When the telegraphic message is sent through the telephone, this method of sending a message is called:
(a) Hologram
(b) Phonogram
(c) Telegram
(d) None of these
Answer:
(b) Phonogram

Question 5.
A key word is used to send telegrams.
(a) Cypher
(b) Code
(c) Travellers
(d) None of these
Answer:
(a) Cypher

UP Board Solutions

Communication System Definite Answer Type Questions (1 Mark)

Question 1.
Name of telegram which are sent by one person to another within the limits of the country.
Answer:
Inland Telegram.

Question 2.
State the full form of I. S. D.
Answer:
International Subscriber Dialing.

Question 3.
What kind of telegram is sent only by government offices and only for official work.
Answer:
State Telegram.

Question 4.
Which letters are sent by sea route?
Answer:
Foreign Letters.

Question 5.
When was speed post service started in India? (UP 2019)
Answer:
1986.

UP Board Solutions

Question 6.
Name the most commonly used accounting software in India. (UP 2019)
Answer:
Tally.

Communication System Very Short Answer Type Questions (2 Marks)

Question 1.
What do you understand by travellers telegram?
Answer:
Telegram can also be delivered to a person travelling (UPBoardSolutions.com) by train. The sender has to write the name of the person, name of the train and number of the bogie and the name of the station at which the train will halt. When the train reaches that station the message is delivered to that person.

Question 2.
Name the various kinds of telegrams.
Answer:

  1. Inland Telegram
  2. Foreign Telegram.

Question 3.
What do you mean by phonogram? (UP 2015)
Answer:
There is a facility provided by the post and telegraph department to send the messages through telephone. This method of sending a message is called ‘Phonogram’. This arrangement of the phonogram is made in the town having telephone. The telephone subscriber can convey the message of telegram to the telegraph office. The department sends the message to the addressee by (UPBoardSolutions.com) telegram and the charge is added to the telephone bill of the subscriber.

UP Board Solutions

Question 4.
Give two differences between code and cypher telegram.
Answer:
Difference between code and cypher telegram.

Code Telegram Cypher Telegram
1. Will the help of code (book) any person can find out the message. Thus the message does not remain secret. 1. Only the persons who know the keyword can find out the message. Thus the message remains secret.
2. The message cannot be communicated without the help of code. 2. Cypher telegrams are sent with the help of code as well as a keyword.

Question 5.
What are the two main advantages of the telegram?
Answer:
Advantages of telegrams are as follows:

  1. If the message is long, then telephone charges would be much more than expenses incurred on telegram.
  2. Telegram is also sent when the message is important and prompt action is required.

Question 6.
Write the names of any two means of quick communication.
Answer:

  1. Telephone
  2. Internet.

Communication System Short Answer Type Questions (4 Marks)

Question 1.
What do you understand by cypher telegram? What are its advantages? (UP 2016)
Answer:
Cypher Telegrams: When the sender wants to keep the message completely secret then cypher telegrams are sent. Such telegrams can be written in digits or letters but usually cypher telegrams are written digits.
Advantages of cypher telegram are as follows:
Only the persons who know the key word can find out the message. (UPBoardSolutions.com) Thus the message remains secret.

UP Board Solutions

Question 2.
Write a note on the utility of telephone.
Answer:
The telephone is the most important means of quick communication. It is also popular because the caller and the receiver both are direct contacts directly with the different parts of the world. Its use is increasing day by day and for this reason, it has become indispensable for a businessman these days. In present times, every business house, industry, insurance companies etc. must essentially have a telephone. The professionals like doctor, lawyer, chartered accountant etc. cannot function properly without a telephone (UPBoardSolutions.com) connection. Without a telephone connection, the working of the business organisations and people in profession will be affected adversely. From the point of view of communication, the telephone has an important place and having a telephone also an indication of reputation and status in society.

Communication System Long Answer Type Questions (8 Marks)

Question 1.
Write notes on S.T.D. and I.S.D. (UP 2008, 10)
Answer:
Subscribers Trunk Dialling (S.T.D.): Under this facility, the person can make trunk calls without the help of a telephone exchange. Now most of the towns have this facility. Suppose a person intends to talk to his friend in Lucknow then he will have to dial the code of the town first and then the number. Each town has a separate code which has STD facility. It is of great importance for the business community as they can make calls at their convenience. In trunk calls the charges are for a minimum period of 3 minutes whereas in STD you have to pay only for the duration of the call which can be less or more than 3 minutes.

International Subscribers Dialling (I.S.D.): These days the telephone service is so advanced that a person can talk to a person sitting in some other country by telephone without the help of the operator. This facility of direct dialling is known as International Subscribers Dialling. Different codes are allotted to every country which are connected by this facility. The subscriber has to dial the international code first i.e., 00 then the country code followed by the area code and at last the overseas telephone number. It is quicker because you have not to book the call and wait till it is matured. There is no limit for duration of the call. A person can talk as long as he wishes and is charged for only the time he talked. It is easier in the sense that the subscriber can call at his convenience whether it is day or night and there is no language problem either.

UP Board Solutions

Question 2.
Write short notes on: (UP 2015)

  1. Teleprinter
  2. FAX System
  3. Internal Telephone Exchange
  4. Radio Paging.

Answer:
1. Teleprinter: Teleprinter is used by major newspapers for collecting news relating to other countries as well as news relating to the native country. A printer is attached to this machine which prints the news on the paper as they are communicated to the office.

2. FAX System: FAX service provides automatic communication through printed words between subscribers in cities and towns provided with Electronic Telephone Exchanges. FAX .subscribers establish their own connections.

3. Internal Telephone Exchange: In big business organizations and offices there are many departments like purchases, sales, accounts, administration etc. Every department has its own officer and each officer has a different (UPBoardSolutions.com) telephone connection so that they can talk to each other on telephone which saves the time of going and coming from one department to another. Under this system, an Internal Telephone Exchange is established within the premises. An operator is appointed who helps in connecting the calls.

4. Radio Paging: This is a one-way communication system. Messages are transmitted to subscribers by means of aerial signals in the form of tone or vibrations through pocket-size receiver called pager. It was introduced in Delhi in 1985. It is now available in all over the country.

UP Board Solutions

Question 3.
Describe the uses of computers in a business office. (UP 2011)
Answer:
Computer is the most important part in a business office.
Following are uses of computers in a business office:

  1. Help in planning: By the help of computer we can collect data which is very helpful in planning.
  2. Help in Finance: Most companies world wide are rapidly switching to a computerised accounting system. Long time consuming calculations and other mathematics-intensive problems can now be solved at the press of a button.
  3. Help in Management: The personal computer has revolutionised manage- ment functions. Computer reduces paper-work, speeds up communication and improves the quality of work.
  4. Help in Accounting: Accounting work in a business office becomes (UPBoardSolutions.com) early with the help of a computer. A computer has made accounting easier with the help of many softwares.
  5. Others:
    • It saves time and money.
    • It seams to have become the backbone of all activities.
    • The computer helps to prepare different reports.
    • It helps to take decisions earlier.

UP Board Solutions for Class 10 Commerce

UP Board Solutions for Class 10 Commerce Chapter 6 Indexing

UP Board Solutions for Class 10 Commerce Chapter 6 Indexing

Indexing Objective Type Questions (1 Mark)

Question 1.
Card indexing was previously used only in:
(a) Libraries
(b) Hostel
(c) Canteen
(d) None of these
Answer:
(a) Libraries

Question 2.
In simple indexing, a special type of book is used bearing letters on the ……….. hand side.
(a) Left
(b) Right
(c) Either (a) or (b)
(d) None of these
Answer:
(b) Right

UP Board Solutions

Question 3.
In vowel inducing each letter is sub-divided in ……….. sub-divisions.
(a) 8
(b) 4
(c) 5
(d) 10
Answer:
(c) 5

Question 4.
When for any reference name card is taken out ………… card in kept in its place.
(a) Index
(b) Absent
(c) Guide
(d) None of these
Answer:
(b) Absent

Question 5.
In the case of card indexing similar names can be clearly distinguished by using cards of …………. colours.
(a) Mix
(b) Different
(c) Black
(d) White
Answer:
(b) Different

UP Board Solutions

Indexing Definite Answer Type Questions (1 Mark)

Question 1.
Write the name of the latest system of indexing?
Answer:
Card index.

Question 2.
What kind of indexing many cards can be seen of a time?
Answer:
Visible Index.

Question 3.
Write the name of the register in which details of outgoing letters arc written. (UP 2014)
Answer:
Despatch Register.

Indexing Very Short Answer Type Questions (2 Marks)

Question 1.
Give any two objects of indexing.
Answer:
Objects of indexing are as follows:

  1. The operation of filing will become (UPBoardSolutions.com) so complicated that it could be happened only by that person who has done filing.
  2. In the absence of indexing, the filing system will become unscientific and incomplete, because it would be a tedious job to find out any document for reference.

UP Board Solutions

Question 2.
What do you mean by Absent cards?
Answer:
When for any reference, name card is taken out, an absent card is kept in its place. It contains all the information regarding the name card as to why is it taken out, who has taken it out and when is it taken out?

Question 3.
What is visible indexing?
Answer:
In visible indexing, cards are arranged in such a manner (UPBoardSolutions.com) that at a time many cards can be seen visible indexing occupies very little space. It can be fitted on the corner of a desk or on a wall.

Question 4.
Name various methods of indexing.
Answer:
Following methods of indexing are adopted by different business houses:

  1. Letter Book or Simple Index
  2. Vowel Index
  3. Card Index
  4. Visible Index.

Question 5.
Give any two advantages of card indexing.
Answer:
Advantages of card indexing are as follows:

1. Cleanliness: In card indexing, the index remains very clean because in this system there is no need to cut the names of those customers with whom the concern has stopped dealing. In this situation, in card indexing, the new card is kept at the appropriate place and the old card is taken out.

2. Time-Saving: This system saves a lot of time. The necessary card is taken immediately with the help of guide cards.

UP Board Solutions

Question 6.
Point out four advantages of card indexing. (UP 2019)
Answer:

  1. Cleanliness
  2. Time-saving
  3. Easy in operation
  4. Elasticity.

Indexing Short Answer Type Questions (4 Marks)

Question 1.
What is Index? Describe its two importances. (UP 2012)
Answer:
Index: The object of filing is to preserve letters and documents in such a manner that they can be found out quickly, whenever they are required for future references. This object of filing can only be made possible (UPBoardSolutions.com) if letters are filed serially according to some particular method. Therefore, a technique is required which can indicate the exact location of a particular letter which is required for the reference and filed in a file. This particular technique is called index.

Importance of Index:

  1. In the absence of an index, it would not be possible to find out the name of the customers who have not placed any order since long.
  2. The employees cannot be held responsible for any delay and inefficiency. It will take a lot of time in finding out the references which will result in delays.

UP Board Solutions

Question 2.
What is a simple indexing? What are the points to be kept in mind in simple indexing?
Answer:
Simple Indexing: For simple indexing, a special type of book which contains thick letters in it is used. In this book, each sheet bears a letter of the alphabet on the right-hand side. Edges of the sheet are cut so that all the letters of the alphabet are seen together. In this, generally, the last page is allotted X, Y and Z, because the names beginning with these letters are generally very small in number.

Following points to be kept in mind in simple indexing:

  1. While writing the names in the book only first name should be considered. The words showing respect should be avoided. For example, name of ‘Thakur Pratap Singh’ should be written in ‘P’, not in T.
  2. Some business houses adopt the technique of writing names on the basis of surnames. They do not write the full name of the customers, but instead of that, they use initials. For example, the name of Shri S. K. Bhatia is written on the page bearing ‘B’.

Indexing Long Answer Type Questions (8 Marks)

Question 1.
What is Card Indexing? Describe its merits and demerits. (UP 2009, 13, 14)
Or
What is the index? What are the advantages of indexing? Describe briefly. (UP 2011)
Or
What is the index? Describe its two importances. (UP 2012)
Answer:
Card Indexing. Card indexing is the latest system in the field of maintaining the index. The system is given the name of “card indexing” for the fact that in it index is made on the card. Card indexing is mainly used in (UPBoardSolutions.com) connection with vertical filing.
The name card which is used in this indexing is made of thick paper which bears the name and address of the correspondent. These name cards are kept in an almirah having many drawers.

This system of card indexing also uses guide cards or index cards which are made of thick paper. These cards are used for the purpose of dividing the drawer into several compartments according to the vowel.
Merits of Card Indexing. Card indexing has several advantages of great value which increase its importance in a business house which are as follows :

1. Cleanliness: In card indexing, the index remains very clean because, in this system, there is no need to cut the names of those customers with whom the concern has stopped dealing. In this situation, in card indexing, the new card is kept at the appropriate place and the old card is taken out.

2. Easy in Operation: In this system, new cards are kept easily without disturbing the others. Whenever a new correspondent appears, his card can easily be inserted in the drawer without disturbing the present order.

3. Time-Saving: This system saves a lot of time. The necessary card is taken out immediately with the help of guide cards.

4. Easy in Finding Cards: The cards can be found out easily and quickly with the use of index or guide cards.

5. Only Current Cards Remain: If the correspondence with any customer is stopped, his card can easily be removed. Thus, only current cards are allowed to remain.

6. Economical and Cheap: This system is quite economical. In a big business house, this indexing is cheaper than ordinary indexing, since the expenses of having a bound book and its occasional renewal with additions to existing correspondents are saved or avoided.

UP Board Solutions

Demerits of Card Indexing: The card indexing also suffers from certain disadvantages. These are as follows:

1. Occupies More Space: This system can be used by big business houses only because it requires more space than simple indexing.

2. Only One Card can be Seen at a Time: In this system, only one card can be seen at a time because each card is in front of another card. Several cards are to be handled for finding out a particular card. For this reason, (UPBoardSolutions.com) this method is known as ‘blind method’.

3. Difficulty in Finding Out Misplaced Cards: If any card is misplaced, it becomes difficult to locate it under this system.

4. Useful for Big Organization Only: The equipment of card indexing are costly, hence, it can only be used by big organizations.

5. Fear of being Lost or Altered: In this system, there is always a fear of the cards being lost or altered.

Question 2.
Describe Card Indexing and explain its utility. (UP 2009)
Answer:
Card Indexing: Card indexing is the latest system in the field of maintaining the index. The system is given the name of “card indexing” for the fact that in it index is made on the card.
This system of card indexing also uses guide cards or index cards which are made of thick paper. These cards are used for the purpose of dividing the drawer into several compartments according to the vowel.

The utility of Card Indexing. The utility of card indexing is as follows:

1. Keeping Files Vertically: Card indexing is particularly used for keeping the files vertically.

2. Address of the Customer: The address of the customer can be written along with the name on the card. This saves the cost of keeping an address book separately.

3. Page Number of the Customer’s Accounts: Sometimes reference of the ledger folio is mentioned in the card. If this is done, there remains no need for providing an index in the account books.

4. Customer’s Economic Condition: All the necessary information regarding the customer’s economic condition can also be written on the card.

5. Name of Customer’s Bank: Name of Customer’s bank can also be written on a card.

6. Pieces of information Regarding Instalments: Nowadays, generally costly goods are sold on instalments. In such cases, the details of the instalments can be written on name cards.

UP Board Solutions

7. Helpful in Follow up System: Sometimes customers maintain silence after making enquiries of the goods and do not place orders. In this case, several letters are sent in order to secure orders. This is called a (UPBoardSolutions.com) Follow-up System of Correspondence. If this system is adopted, the card indexing is of great help. On receiving an enquiry from the customer, its reference may be written on his name card. The reference of the letters sent in reply can also be given on his name card.

8. Customer’s Business: On the name cards, nature of the business of the respective customers may be written, This helps in sending and securing goods from the customers. The important terms and conditions of business can also be written on name cards.

9. Preservation of Price-List etc: Price-lists and other information received from the customers can also be preserved on the name cards.

10. Informations Regarding Credit: When goods are sold on credit then it is convenient to maintain the reference regarding the period and maximum amount of credit allowed to the customers on the name card.

UP Board Solutions for Class 10 Commerce

UP Board Solutions for Class 10 Commerce Chapter 15 Co-Operative Banks

UP Board Solutions for Class 10 Commerce Chapter 15 Co-Operative Banks

Co-Operative Banks Objective Type Questions (1 Mark)

Question 1.
Indian Co-operative Society Act was passed in the year:
(a) 1902
(b) 1904
(c) 1906
(d) 1908
Answer:
(b) 1904

Question 2.
Liability of the members of the Rural Co-operative Credit Society is:
(a) Unlimited
(b) Limited
(c) Either (a) or (b)
(d) None of these
Answer:
(a) Unlimited

UP Board Solutions

Question 3.
Mainly the …………. are the members of Rural Co-operative Credit Society.
(a) Villagers
(b) Farmers
(c) Businessman
(d) None of these
Answer:
(b) Farmers

Question 4.
Central Co-operative Banks are situated in ………
(a) Each town or Village
(b) Each Country
(c) Each district or tehsil of the state
(d) None of these
Answer:
(c) Each district or tehsil of the state

Question 5.
The President of India passed an ordinance on ………… for the establishment of Regional Rural Banks.
(a) 23rd Sept 1975
(b) 25th Aug 1975
(c) 22nd Aug 1975
(d) 22nd Sept 1975
Answer:
(d) 22nd Sept 1975

UP Board Solutions

Co-Operative Banks Definite Answer Type Questions (1 Mark)

Question 1.
What is the authorised capital of Regional Rural Bank?
Answer:
One crore.

Question 2.
How many members required to form Primary Co-operative Credit Societies?
Answer:
Ten Persons

Question 3.
In which schedule Regional Rural Banks are included by the Reserve Bank of India?
Answer:
Schedule II.

Question 4.
How many branches were established in Uttar Pradesh of Regional Rural Banks till September 1982?
Answer:
326.

UP Board Solutions

Co-Operative Banks Very Short Answer Type Questions (2 Marks)

Question 1.
How the condition of these societies can be improved? Give any two suggestions.
Answer:
Suggestions for improving Co-operative Banks are as follows:

  • The people should be made educated in (UPBoardSolutions.com) order to make them understand the importance of co-operation.
  • The employees should be taught the banking principles which will help in the proper management of the banks.

Question 2.
Give types of Co-operative Banks? (UP 2016)
Answer:
Kinds of Indian Co-operative Banks are as follows:

  1. Primary Co-operative Credit Society.
    • Rural Co-operative Society
    • Urban Co-operative Society.
  2. Central Co-operative Bank.
  3. Provincial or State Co-operative Bank.

UP Board Solutions

Question 3.
Write two drawbacks of Co-operative Credit Societies?
Answer:
Two drawbacks of co-operative credit societies are as follows:

  • Illiteracy: In our country major portion of the population is uneducated and they do not understand what is the corporation.
  • Dishonest Members and no proper records are kept: (UPBoardSolutions.com) The records of these societies are not kept properly nor they are audited. The members are dishonest and indulge in fraudulent practices.

Co-Operative Banks Short Answer Type Questions (4 Marks)

Question 1.
Distinguish between Rural Co-operative Credit Society and Urban Co-operative Credit Society.
Answer:
Difference between Rural and Urban Co-operative Credit Society.

Rural Co-operative Credit Society Urban Co-operative Credit Society
1. The rural co-operative credit society functions in a village and the farmer are generally its members. 1. Urban co-operative credit society functions in a town and mostly its members are residents of that town.
2. The liability of the members is unlimited. 2. The liability of the members is limited.
3. The profits are not distributed and if at all they are distributed the quantity is very small. 3. The profits are distributed and only 25 per cent of the profits have to be kept in reserve funds.
4. Only a few employees are paid salary and the rest are unpaid. 4. Comparatively more employees are paid salary.
5. The circulation of shares is very nominal. 5. The shares remain in circulation in good quantity.
6. The objective of these societies is to give economic help to the farmers. 6. The objective is to give financial assistance to poor labourers artisans etc. of the town.

UP Board Solutions

Co-Operative Banks Long Answer Type Questions (8 Marks)

Question 1.
What are the causes of failure of the cooperative banks in our country? What steps should be taken to make them useful? (UP 2019)
Answer:
Defects of Co-Operative Banks or Credit Societies
The Co-operative movement in our country could not get the desired success. The Co-operative Banks have been able to solve the problem of rural debts in a very small area. The main reason for it, are the (UPBoardSolutions.com) defects in co-operative credit societies which are as follows :
1. Illiteracy: In our country major portion of the population is uneducated and they do not understand what is co-operation.

2. Self Interest of Members: The members of the society provide loans to their friends and relatives because of which other members are not benefitted and do not get the facility of loan. Sometimes it also happens that these loans are not recovered from the friends and relatives of the members.

3. Improper Functioning: In rural areas, the members responsible for the proper functioning of society do not have knowledge of banking, so they are unable to handle the affairs properly.

4. Dishonest Members and no proper records are kept: The records of these societies are not kept properly nor they are audited. The members are dishonest and indulge in fraudulent practices.

5. Lack of Co-operation: The basic principle of co-operative societies is co-operation and co-ordination among the members, but in India, we find that it lacks among the members. In every village of our country there is groupism, (UPBoardSolutions.com) casteism, etc. then under these circumstances how can we expect co-operation and co-ordination among the members.

UP Board Solutions

6. Lack of Funds: The Indians are poor and they are not able to deposit money with the societies which result in lack of funds with the society. Due to lack of funds, the members are not able to get the loans according to their needs.

7. A problem in getting Loan: The members face problem in getting the loan because before giving the loan, the society checks the credibility of the member and other formalities have to be completed. All this takes a lot of time and the member is unable to get the loan at the time of need. Ultimately they have to take a loan from money-lenders or Mahajan.

8. Government’s Intervention: The people do not have much faith in societies because of the government’s intervention.in them. The major defect of the Indian Co-operative movement is that it has been implemented by the government requiring the fulfilment of a lot of many formalities and for this reason, the people do not have any interest towards this movement.

9. The high rate of Interest: The rate of interest charged by these societies is high because they do not have adequate funds and they have to borrow from others. These societies borrow money from Central Co-operative Banks at a higher rate of interest. The rate of interest charged by these societies should be normal So that there is no burden on the members. Generally, the rate (UPBoardSolutions.com) of interest charged by these societies is ranging in between 10% to 14%.

10. The problem of loan repayment: The loans are not repaid by the members in time. As already told that the societies do not have adequate funds and when the loans are not repaid in time, these societies face an uphill task. The outstanding loans are increasing day by day and major portion of the debts become bad.

11. Societies only provide financial assistance: The Co-operative societies only provide financial assistance whereas they should also perform the activities of sale and purchase. Multi-purpose co-operative societies can only take out the people of rural areas from the grip of the Mahajan’s.

12. A very little number of people becoming members: All the persons are unable to become members of society. Thus, only a small number of persons who are financially sound take advantage of society.

13. Poor Financial Condition: The financial condition of these societies is always very weak. When they do not have adequate funds then how can they provide financial assistance to others? The members do not take much interest in society because their financial needs always remain unfulfilled.

14. Only influential persons become members: The persons who are wealthy or those who have a political approach become the members of these societies. The poor people do not get any assistance from these societies in spite of the fact that these societies are meant for poor.

15. Political Interference: These societies are now in the grip of the political leaders and the basic principle for the formation of these societies has been defeated by these leaders. In many places, these leaders have formed the co-operative societies which are closed after receiving aid from the government.

UP Board Solutions

Suggestions for Improving Co-Operative Banks
Suggestions for improving Co-operative Banks are as follow:

  1. The people should be made educated in order to make them understand the importance of co-operation.
  2. The employees should be taught the banking principles which will help in the proper management of the banks.
  3. Only short term loans should be given so that all the members are benefitted.
  4. The penalty should be imposed if the loans are not repaid in time.
  5. Before giving the loan it should be checked whether the loan is being given for productive needs or not.
  6. The Central Bank should give loan to these societies on a lower rate of interest.
  7. The records should be properly kept by these societies which should be inspected and audited from time to time so that fraudulent practices are minimised.
  8. There should be a maximum limit for granting a loan and no member should be given loan more than the maximum limit.
  9. The principles of co-operative should be made known to the public.
  10. The government should also help these societies according to their needs.
  11. These societies should increase their reserve funds which will make their financial position strong.
  12. Instead of competing with these societies, the Commercial Banks should provide assistance to them.
  13. In addition to co-operative credit societies, multi-purpose (UPBoardSolutions.com) co-operative societies should be formed so that they could also help the people in other walks of life.
  14. These societies should be kept free from politics and there should be minimum interference of the government.
  15. The co-operative societies should try to get deposits so that their financial position will become strong.

UP Board Solutions

Question 2.
Describe the achievements of Co-operative moment in India. (UP 2011)
Answer:
Achievements of the Co-operative Movement in India: The main achievements of the Co-operative Movement in India are as below:

  1. Co-operation: It has encouraged a feeling of co-operation among rural people towards economic progress.
  2. The decrease in the influence of sahukars: The contribution of chukars to rural credit has come down to about 16 per cent from earlier 70 per cent contribution.
  3. The decline of conservative attitude: The co-operative movement has significantly modified the conservative attitude of rural people to a give-up the ancient custom of death-feast, etc.
  4. Cheap credits: The interest charged by the co-operatives is much less than that charged by sahukars and so rural people now avail the facility of cheap credits.
  5. Amount of loans: The amount of loans given to rural industries and agriculture has increased substantially and since it is quite cheap, these people have been appreciably benefitted.
  6. Reduction of debts on farmers: Because of credit co-operatives, the debts on farmers are regularly reducing.
  7. New methods of agriculture: The credit co-operatives have guided the farmers to learn to adopt new and improved methods, and for purchasing various equipment, cheap credits have been made available by these co-operatives.
  8. New hope for development: Because of the co-operative movement, a new hope of economic development has encouraged rural people for doing hard work.
  9. The habit of thrift: Since the facilities of deposits have reached their doorsteps, the habit of thrift has been inculcated amongst the rural people.
  10. Storage and marketing: Co-operative societies now help in arranging facilities of storage and marketing to farmers. A farmer can now sell his produce through co-operative society.
  11. Economic improvements: Non-credit societies like Housing Co-operatives, (UPBoardSolutions.com) Consumer Co-operatives, etc., have helped in achieving economic improvements among rural and urban people.

UP Board Solutions

Question 3.
Point out the distinguishing features of Co-operative Bank and Commercial Banks. (UP 2009)
Answer:
Difference between Co-operative Bank and Commercial Banks:

Co-operative Bank Commercial Banks
1. Co-operative Banks grants loan only to its members and not to everyone. 1. Commercial Banks accept deposits from people and grant loans to every needy person.
2. Co-operative Bank gives loans to its members for their economic development. 2. Commercial Banks give loan for promoting trade and industry of the country.
3. The object of these banks is to assist poor and unresourceful people. 3. Commercial Banks give loan against some security.
4. These banks not only give loans but they also inspire others to save and become independent. 4. The work of these banks is to provide loans and not to give moral preachings.
5. Every member of the co-operative bank has a responsibility towards the bank. 5. In Commercial Banks, the manager and the Directors look after the management of the bank.
6. The co-operative banks are regulated by the Indian Co-operative Society Act, 1904. 6. The Commercial Banks are regulated by the Indian Companies Act and Banking Regulation Act.
7. The motive of these banks is not to earn profit but to give facilities to its members. 7. The motive of these banks is to earn the profit.
8. The rate of interest is low. 8. The rate of interest (UPBoardSolutions.com) charged by these banks is high.
9. These banks provide loans only for production needs. 9. These Banks give loans of any kind, whether productive or not.

UP Board Solutions

Question 4.
Write the importance of Co-operative Bank in Rural Economy. (UP 2008, 11, 13)
Answer:
Importance of Co-operative Bank in Rural Economy. India is a country of villages. The people living in rural areas are poor. The development of the country depends upon the economic development of the villages. The financial position of our rural areas was never good and because of it, our agriculture could not improve. Someone has rightly said: “The Indian farmer horns in indebtedness leads his life in indebtedness and dies leaving the burden of indebtedness on his heirs.”

The shortage of funds for agriculture purposes are fulfilled by money-lenders or Mahajan. The money-lenders charge a very high rate of interest because they enjoy the monopoly. The poor farmers are unable to repay the loan and are always at the mercy of the money-lenders. The cottage industries do not prosper due to lack of financial assistance. The artisans to have to depend on the money-lenders.

Question 5.
What is the Co-operative Bank? Describe its importance also. (UP 2014)
Answer:
Co-operative Bank: When some persons join together to form a society and start accepting deposits and provide loans to their members then that society is known as Co-operative Bank or Co-operative Credit Society. The main objective of the Co-operative Bank is to provide financial assistance to people who are poor and do -not have any resources. These banks accept (UPBoardSolutions.com) small deposits from the members and often ask the members to subscribe to the share capital of the bank. The bank helps the members of the bank by giving them loans for productive needs from time to time.

UP Board Solutions

Importance of Co-operative Bank:
The main object of Co-operative Banks is to provide financial assistance to poor. Following are the main advantages of Co-operative Banks:

  1. The rate of interest charged is low and the needy have not to go to the money-lenders for financial assistance.
  2. The people develop the habit of saving.
  3. The members gain confidence as all of them work with the Co-operation of each other.
  4. People become independent and they have not to depend on others. They also develop a feeling of responsibility.
  5. Agriculture and industry receive encouragement.
  6. People are encouraged to utilise their money for (UPBoardSolutions.com) productive functions.
  7. Development of agriculture and cottage industries makes the farmers financially sound.

UP Board Solutions for Class 10 Commerce

UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque Objective Type Questions (1 Mark)

Question 1.
A cheque cannot be crossed by (UP 2014)
(a) Drawer
(b) Payee
(c) Endorser
(d) Bank
Answer:
(b) Payee

Question 2.
Which kind of cheque is complete in all respects except the amount payable?
(a) Post Dated Cheque
(b) Bearer Cheque
(c) Blank Cheque
(d) Order Cheque
Answer:
(c) Blank Cheque

UP Board Solutions

Question 3.
Bill of Exchange is accepted by (UP 2013)
(a) Drawer
(b) Drawee
(c) Payee
(d) Banker
Answer:
(b) Drawee

Question 4.
Bearer cheque received by the payee ………. crossed. (UP 2013)
(a) Can be
(b) Cannot be
(c) Not known
(d) All of these are incorrect
Answer:
(a) Can be

Question 5.
Signature of the drawer on cheque is: (UP 2012, 16)
(a) Not necessary
(b) Desirable
(c) Necessary
(d) All of these are incorrect
Answer:
(c) Necessary

Question 6.
In ……… type of crossing of cheque the name of the bank is mentional between two parallel lines: (UP 2015, 17)
(a) General
(b) Special
(c) Restrictive
(d) None of these
Answer:
(b) Special

UP Board Solutions

Question 7.
Days of Grace in paying bills of exchange are: (UP 2019)
(a) 2
(b) 3
(c) 7
(d) 30
Answer:
(b) 3

Question 8.
‘Liability on Bills discounted’ is: (UP 2019)
(a) Fixed liability
(b) Current liability
(c) Contingent liability
(d) None of these.
Answer:
(c) Contingent liability

Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque Definite Answer Type Questions (1 Mark)

Question 1.
Name the cheque which can be cashed at the window of the bank by any person.
Answer:
Bearer.

Question 2.
Under which endorsement endorser puts the name of endorsee on back of the cheque?
Answer:
Special or full.

Question 3.
In which year does the Negotiable Instrument Act enact?
Answer:
1881.

Question 4.
How many parties are there to a Bill of Exchange?
Answer:
Three.

UP Board Solutions

Question 5.
Who draws a Bill of Exchange?
Answer:
Seller or Debtor.

Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque Very Short Answer Type Questions (2 Marks)

Question 1.
What is cheque? Write the names of three parties of cheque. (UP 2013)
Answer:
Cheque: Cheque is a Bill of Exchange drawn on a specified banker and not expressed to be payable otherwise than on demand.
Parties of Cheque:

  1. Drawer: The person who has (UPBoardSolutions.com) written the cheque and sign it.
  2. Bank: The place which gives payment to the payee in order to cheque’s drawer.
  3. Payee: The person who receives the payment.

Question 2.
Define a promissory note. (UP 2013, 18)
Answer:
A Promissory Note is legally defined as, “an unconditional promise in writing made by one person to another, signed by the maker engaging to pay on demand or at a fixed or determinable future time a sum certain money to or to the order of a specified person.”

Question 3.
What is Bill of Exchange? Write the names of the two parties of Bill of Exchange. (UP 2012, 14, 15)
Answer:
Bill of Exchange: When goods are sold on a credit basis, the businessman does not get cash immediately, but he gets it after a stipulated time. In the mean-time, he is supplied with a written acknowledgement of debt, which known as Bills of Exchange.
Parties of Bills of Exchange:

  1. Drawer: He is the person who writes or draws the Bills of Exchange.
  2. Drawee: Drawee is a person on whom Bill of Exchange has been drawn.
  3. Payee: Payee is the person to whom the amount (UPBoardSolutions.com) mentioned in the Bill is paid.

UP Board Solutions

Question 4.
Define a Promissory note and write the names of its parties. (UP 2019)
Answer:
A promissory note is legally defined as “an unconditional promise in writing made by one person to another. Signed by the maker, engaging to pay on demand or at a fixed or determinable future time a sum certain money to or to the order of a specified person.”
Parties of Promissory note:

  1. Maker
  2. Payee.

Question 5.
Define Hundi. (UP 2012)
Answer:
Hundis were in circulation even when the banks did not exist. Hundis are private credit instruments of the Government has no control over them. Hundi may be written in any of the regional languages of India. Hundis are written for a fixed period or are payable on demand.

Question 6.
When is Bill of Exchange is dishonoured? (UP 2013)
Answer:
The bill is dishonoured when the drawee is unable to make the payment on the maturity of the bill. When a bill is dishonoured, immediate notice should be given to the drawee and to the endorser. If this is not done, (UPBoardSolutions.com) the holder of the bill cannot for the due amount.

Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque Short Answer Type Questions (4 Marks)

Question 1.
Distinguish between Bills of Exchange and Hundi.
Answer:
Difference Between Bill of Exchange and Hundi

UP Board Solutions

Bill of Exchange Hundi
1. Bill of Exchange is governed by Indian Negotiable Instrument Act, 1881. 1. Hundi is not governed by any Act i.e., the government has no control and interference over it.
2. Bill of Exchange is generally written in the English Language. 2. Hundi is written in Hindi or may be written in any regional language.
3. Bill of Exchange is always unconditional. 3. Hundi may be conditional as well as unconditional also.
4. Acceptance is required in case of a Bill of Exchange. 4. Acceptance is not required in case of a Hundi.
5. Bill of Exchange is universally accepted i.e., it can be used all over the world. 5. The use of Hundi in limited within India.

Question 2.
How is a cheque crossed? Point out its two advantages. (UP 2019)
Answer:
Crossing a cheque means drawing two oblique lines on the face of the cheque on the upper left corner. The crossing of a cheque is of following two types:

  1. General crossing
  2. Special crossing

Two advantages:

  1. Crossing a cheque makes it difficult for a wrong person to get payment of the cheque.
  2. Payment of money only through an account with the (UPBoardSolutions.com) bank and not in cash.

UP Board Solutions

Question 3.
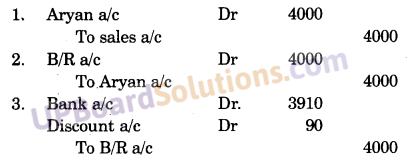
On 1st March 2018, Dev sold goods worth Rs. 4,000 to Aryan and received a bill for the period of three months against its payment. Dev discounted the bill at 9% with the bank on the same day. The bill was dishonoured on the date of maturity and the bank paid Rs. 50 as Noting charges.
Pass necessary journal entries in the books of Dev. (UP 2019)
Answer:
Journal entries in the books of Dev:
UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque Long Answer Type Questions (8 Marks)

Question 1.
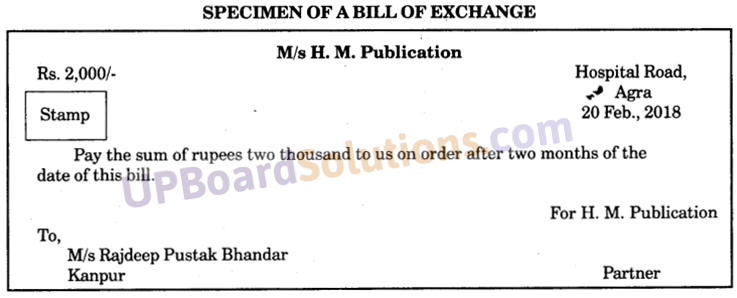
What do you understand by Bill of Exchange? Differentiate between Cheque and Bill of Exchange and also draft their specimen. (UP 2003, 10, 11)
Or
Define Bill of Exchange. Distinguish between Bill of Exchange and Promissory Note. (UP 2005)
Or
Differentiate between cheque and Bill of Exchange. (UP 2014)
Or
What is Bill of Exchange? Write the names of the two parties of Bill of Exchange. (UP 2012, 16)
Or
What is Cheque? Write the name of three particles of a cheque. (UP 2013)
Answer:
Meaning of Bill of Exchange: When goods are sold on a credit basis, the businessman does not get cash immediately, but he gets it after a stipulated time. In the meantime, he is supplied with a written acknowledgement (UPBoardSolutions.com) of debt, which is known as Bills of Exchange.
Difference between Bill of Exchange and Cheque:

Bill of Exchange Cheque
1. It may be written on both individual or firm. 1. It is written only on any specific bank.
2. It may be for a fixed term or payable at sight. 2. It is always payable on demand.
3. Acceptance is a must in case of it. 3. Acceptance is not just in case of a cheque.
4. It may be payable both in-country as well as outside the country. 4. Cheque is payable only within the country.
5. It cannot be crossed. 5. It may be crossed.
6. It is compulsory to stamp it. 6. It is not necessary to stamp it.
7. Three days of grace are allowed. 7. No day of grace is allowed.
8. Noting is a must in case of dishonour. 8. Noting is not just in case of dishonour.

UP Board Solutions

UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque
Difference between Bill of Exchange and Promissory Note:

Bill of Exchange Promissory Note
1. Bill of Exchange is defined under Section 5 of the Negotiable Instrument Act, 1881. 1. Promissory Note is defined under Section 4 of the Negotiable Instrument Act, 1881.
2. Acceptance is necessary in case of Bill of Exchange. 2. No such question of acceptance arises in case of Promissory Note.
3. Bill of Exchange contains an order for payment. 3. Promissory Note contains promise for payment.
4. The drawer of Bill of Exchange is the creditor. 4. The drawer of Promissory Note is the debtor.
5. The dishonour of Bill of Exchange may be noted to the Notary. 5. No such Noting is required in case of a Promissory Note.
6. There may be three pen-ties to the Bill of Exchange: Drawer, Drawee and Payee. 6. There are two parties to the Promissory Note: Drawer and the Receiver.
7. The drawer of Bill may become the payee for Bill of Exchange. 7. The drawer of the Bill cannot be the receiver for Promissory Note.
8. Bill of Exchange payable on presentation does not require a stamp. 8. Stamp is required in all kinds of Promissory Notes.

UP Board Solutions

Question 2.
Under what conditions an Accommodation Bill is written and how is it different from a Trade Bill?
Answer:
Accommodation Bills are written under the following conditions:
1. A trader draws a bill on the other trader and gets his acceptance. He then discounts it with the bank and uses the money. He sends the money to the acceptor before the due date and the acceptor meets the bill on the due date.

2. A trader draws a bill on the other trader and gets his acceptance. He then discounts the bill with the bank. Then both the traders divide the amount and discount among themselves in a pre-determined ratio. (UPBoardSolutions.com) Before the date of maturity, the drawer sends his share of money to the acceptor and the acceptor meets the bill on the maturity date.

3. Sometimes both the traders draw a bill on each other. Both the bills may be of the same amount or maybe of different amounts. The traders discount the bills with the respective bank and on the due date, each of them pays off his respective bill.

Differences between Accommodation Bill and Trade Bill:

Basis of Difference Accommodation Bill Trade Bill
1. Basis It is not on the basis of the business transaction. Its basis is the business transaction.
2. Return It is not written for any valuable return. It is drawn for getting a valuable return.
3. Objective These bills are drawn to remove temporary financial difficulties. These bills are drawn by one party on another to realise the amount.
4. Payment by Bank Bank hesitates to make the payments of such bills. Bank does not hesitate for making the payments of such bills.
5. The relation between Debtor and Creditor Relationship of Debtor and Creditor does not exist between the writer and acceptor of the bill. Debtor and Creditor relationship exists between the writer and acceptor of the bill.

Question 3.
What do you understand by ‘Dishonour of a Bill’? Give journal entries of Dishonour of Bill in the books of drawer and drawee.
Answer:
Meaning of Dishonour of Bill. The bill is dishonoured when the drawee is unable to make the payment on the maturity of the bill. When a bill is dishonoured, immediate notice should be given to the drawee and to (UPBoardSolutions.com) the endorser. If this is not done, the holder of the bill cannot claim for the due amount.

All the expenses incurred, relating to the dishonour of the bill should be debited to the person from whom the bill was received.
The acceptor of the bill is primarily liable for payment, but the holder has a right to take actions against the drawer and other endorsers of the bill. Usually, the drawer takes up the bill dishonour and then exercises his right against the drawee.
Journal Entries in the books of a drawer under the five possibilities are as follows:

UP Board Solutions

1. When the bill is retained with him, till the date of maturity
Acceptor’s A/c Dr.
To Bills Receivable A/c
To Cash A/c
(Being Bill dishonoured and noting charges paid in cash)
Note: If noting charges are not paid then Cash A/c is not credited, the amount of bill is mentioned in the entry.

2. When the drawer gets the Bill discounted with a bank:
Acceptor’s A/c Dr.
To Bank A/c
(Being Bill dishonoured and noting charges paid by the bank)

3. When the Bill is endorsed by the drawer:
Acceptor’s A/c Dr.
To Creditor’s A/c
(Being Bill dishonoured and noting charges added)

4. When the drawer deposits the Bill with bank for collection.
Acceptor’s A/c Dr.
To Bill for collection A/c
To Bank A/c
(Being Bill dishonoured and noting charges paid by the bank)

5. In the book of drawee journal entries when Bill is dishonoured.
B/P a/c Dr.
(If given )Noting charges a/c Dr.
To Drawer
(Being Bill dishonoured and Noting charged paid)

Question 4.
What do you understand by a Hundi and Promissory Note? Give the specimen of a promissory note. (UP 2008, 10)
Or
Define Hundi. (UP 2012)
Or
What do you mean by promissory note? UP 2012)
Or
Define the promissory note. (UP 2013)
Answer:
Hundi: Hundi is also a very popular credit instrument among the Indian businessmen from times immemorial. Even in today’s world, Hundi is used by most of the Indian businessmen. Hundreds were in (UPBoardSolutions.com) circulation even when the banks did not exist. Hundies are of different nature from Bills of Exchange. Since Hundies are private credit instruments, the Government has no control over them. Hundi may be written in any of the regional languages of India. Hundies are written for a fixed period or are payable on demand.

Promissory Note: There is another method by which the promise made by the purchaser to pay for goods bought by him can be made which is definite and absolutely binding upon him. Such a promise is signed by the debtor and is handed over to the creditor, is called a ‘Promissory Note’.

A Promissory Note is legally defined as, “an unconditional promise in writing made by one person to another, signed by the maker, engaging to pay on demand or at a fixed or determinable future time a sum of certain money to or to the order of a specified person.”

UP Board Solutions
UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque
There are only two parties of Promissory Note. The person who has written the Promissory Note and signs it, is known as the ‘maker’. In the given specimen S.K. & Co. is the maker. The person who receives the payment is known as ‘Payee’. In the given specimen, R. S. & Sons are the payees.

Question 5.
Sanjeev sold goods worth Rs. 2,000 to Amit on 1st March 2011 and received a bill of exchange for three months and on the same date, Sanjeev endorsed it in favour of his creditor Mr Prakash. Bill was dishonoured on the due date and Prakash got it noted paying Rs. 50 for noting charges. Pass Journal Entries in the books of Sanjeev, Amit and Prakash.
Solution:
UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

UP Board Solutions

Question 6.
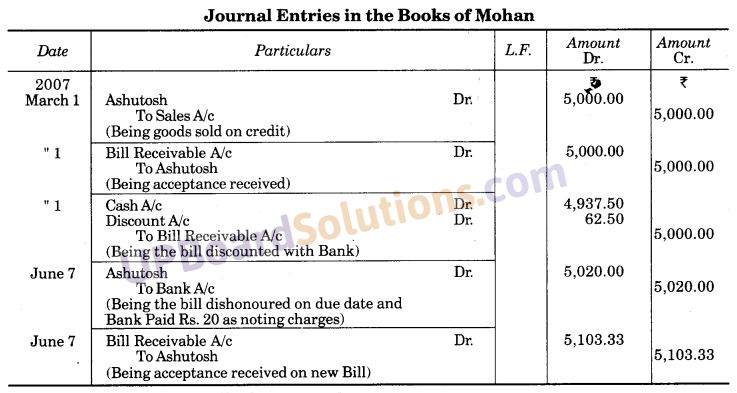
On 1st March 2007, Mohan sold goods of Rs. 5,000 to Ashutosh on credit. On the same date, Ashutosh accepted a bill for a period of three months of the same amount. Mohan discounted this bill from the Bank @ 5% p.a. The bill was dishonoured on the due date. The bank paid Rs. 20 as noting charges.
On June 4, 2007, Ashutosh accepted a new bill for two months. (UPBoardSolutions.com) The new bill was written with the amount of old bill noting charges and interest @ 10% p.a. Give the journal entries in the books of Mohan. (UP 2008)
Solution:
UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

Question 7.
Sunil drew a bill of ₹ 20,000 for 3 months on 1st January 2011 which was accepted by Anand; Sunil discounted the accepted bill from his Bank on the same day and allowed @ 5% p.a. discount. Sunil paid the full amount to Anand before a day from the due date. On due date, Anand duly paid the bills of exchange.
Make journal entries to record these transactions in the books of Sunil and Anand. (UP 2010)
Solution:
UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

UP Board Solutions

Question 8.
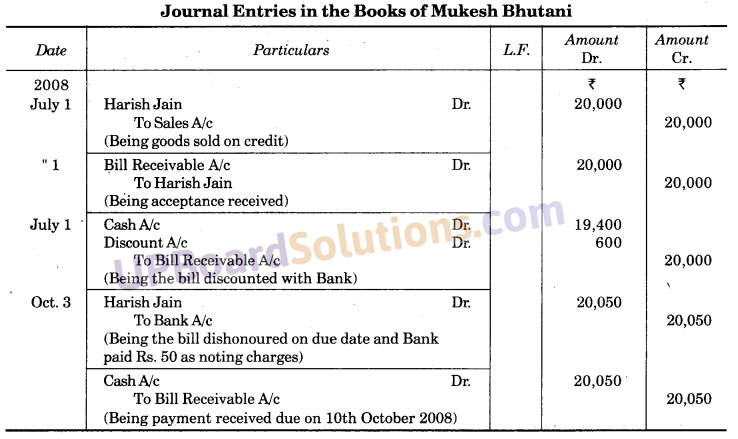
Mukesh Bhutani sold goods worth Rs. 20,000 to Harish Jain on 1st July 2008. Mukesh Bhutani drew a bill of the same amount payable after three months which was returned by Harish Jain after accepting it. On the same date, Mukesh Bhutani discounted the bill @ 12% per annum. Bill was dishonoured on the due date and Rs. 50 was paid by the bank as noting charges. Harish Jain paid the whole amount due On 10th October 2008.
Pass Journal Entries in the Books of Mukesh Bhutani. (UP 2009)
Solution:
UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

Question 9.
On January 1, 2011, Sukesh sold goods of Rs. 25,000 to Neelesh. Sukesh drew a bill for a period of two months. Bill was accepted by Neelesh. On January 16, 2011, bill was discounted by Sukesh with his bank @ 15% p.a. On the due date, bill was paid by Neelesh.
Pass Journal entries in the books of Sukesh and Neelesh. (UP 2011)
Solution:
UP Board Solutions for Class 10 Commerce Chapter 4 Credit Instrument: Bills of Exchange, Hundi, Promissory Note and Cheque

UP Board Solutions

Question 10.
Write the answer to the following questions:

  1. Define Bill of Exchange. (UP 2014)
  2. What are the two kinds of a Bills of Exchange?
  3. What is meant by Promissory Note?
  4. Write the model of crossing a cheque? (UP 2014)
  5. What is meant by Rebate and Retired?
  6. What is Accommodation Bill?

Answer:

  1. “A Bill of Exchange is an instrument in writing, containing an unconditional order signed by the maker, directing to pay a certain sum of money after a certain period to him or to the order of a certain person or to the bearer of the instrument”.
  2. Two kinds of Bills of Exchange are very much popular:
    • Bill of Exchange payable on-demand or on presentation, and
    • Bill of Exchange payable after a specific period.
  3. It is another method by which the promise made by the purchaser to pay for goods bought by him can be made which is definite and absolutely binding upon him. Such a promise signed by the debtor and handed over to the creditor is called a ‘Promissory Note’.
  4. There are two modes of crossing a cheque:
    • General Crossing: It is only drawing two (UPBoardSolutions.com) oblique parallel lines on the face of the cheque same times with the words ‘& Co.’ Not Negotiable.
    • Special Crossing: This is a special type of crossing of cheque in which the name of certain bank is mentioned between two parallel lines.
  5. When the financial position of the drawee is sound, he pays the bill before the due date, it is said to have been ‘retired under discount’ as the party making the payment receives some discount. This discount is known as ‘Rabate’ and payment of bill before the due date is called ‘Retired’.
  6. An Accommodation bill is a Bill of Exchange for which no consideration is given by the drawer to the acceptor, but which has been drawn and accepted by the parties concerned for their mutual accommodation with a view to raise money by negotiating it.

UP Board Solutions for Class 10 Commerce